Nvidia's $100 Billion Investment in OpenAI - Analyzing the "Customer Financing" Model and its Strategic Implications
Is Nvidia's $100 billion investment in OpenAI a visionary move to secure its AI dominance for the next decade, or a high-stakes financial engineering gambit that blurs the lines between supplier and customer, inviting scrutiny and unforeseen risks?


NVIDIA and OpenAI's Strategic Partnership: A Glimpse into the "Customer Financing" Model in the AI Era
In an era of rapid AI technology advancement, the demand for high-performance computing capabilities has reached unprecedented levels. The recent announcement of NVIDIA's investment of up to $100 billion in OpenAI for the deployment of its 10GW AI infrastructure has not only shocked the market but also sparked widespread discussion on the "customer financing" model in the AI industry and its far-reaching implications. This article will delve into the strategic significance and financial considerations of this collaboration, comparing it against the backdrop of OpenAI's past dealings and NVIDIA's partnerships with "neo cloud" companies like CoreWeave.
1. Partnership Overview: The Monumental Alliance Between NVIDIA and OpenAI
NVIDIA and OpenAI announced a Letter of Intent (LOI) for strategic cooperation on September 22, 2025, aiming to jointly build and deploy OpenAI's next-generation AI infrastructure. Under the agreement, OpenAI plans to deploy at least 10GW of NVIDIA systems, which will include millions of NVIDIA GPUs, to support the training and operation of its next-generation AI models. In return, NVIDIA plans to progressively invest up to $100 billion in OpenAI, with investments tied to the deployment of each GW system. The first 1GW system, featuring NVIDIA Vera Rubin GPUs, is expected to begin generating its first tokens in late 2026. NVIDIA will become OpenAI's preferred strategic computing and networking partner, with both parties working closely to optimize OpenAI's models and infrastructure software with NVIDIA's hardware and software roadmaps.
This partnership is viewed by analysts as a significant boon for NVIDIA and its supply chain, projected to generate potential revenue of $200 billion to $500 billion for NVIDIA, roughly equivalent to the current Total Addressable Market (TAM) for AI computing. BNP Paribas estimates that this 10GW collaboration will add an extra 20% to the global AI infrastructure's total capital expenditure.
2. Strategic Considerations of the "Customer Financing" Model: Solidifying Ecosystem, Accelerating Innovation
NVIDIA's substantial investment in OpenAI is a prime example of its strategic deployment of massive Free Cash Flow (FCF). With $200 billion in revenue and ~40-50% FCF margins, NVIDIA is projected to generate tens of billions in FCF over the next few years. By investing in its ecosystem, NVIDIA can expand its addressable market opportunities, multiply future earnings, accelerate time-to-market for new products, and yield geopolitical benefits.
2.1 The CoreWeave Case: A Successful Paradigm of NVIDIA's "Customer Financing"
NVIDIA's partnership with CoreWeave stands as an early and successful example of its "customer financing" model. NVIDIA not only invested $100 million in CoreWeave but also prioritized the supply of hundreds of thousands of high-end GPUs to the company. Furthermore, the two companies implemented "Project Osprey," where NVIDIA would lease back its own manufactured chips from CoreWeave for $1.3 billion over four years, making NVIDIA CoreWeave's second-largest customer.
CoreWeave's successful transformation is inextricably linked to NVIDIA's support. In 2021, the company's primary revenue came from Ethereum mining, but it rapidly pivoted to the AI business after the cryptocurrency price downturn in September 2022. NVIDIA's commitment, coupled with over $4 billion in orders from Microsoft, helped CoreWeave secure $2.4 billion from investors like Blackstone to build more data centers. CoreWeave's success is attributed to NVIDIA's GPU allocation strategy, efficient deployment speed, and strategies for data center resource acquisition.
Through this model, NVIDIA achieves multiple strategic objectives:
- Secure GPU Demand: By investing and prioritizing supply, NVIDIA locks in demand for its GPUs from key customers.
- Expand Market Share: Supporting "neo cloud" companies like CoreWeave creates an incremental market for NVIDIA's GPU ecosystem, avoiding over-reliance on hyperscale cloud providers such as AWS and Microsoft Azure who might develop their own AI chips.
- Drive Down Commoditization Prices: By supporting smaller cloud companies, NVIDIA can influence the commoditization prices of GPUs, preventing profits from being absorbed by large cloud vendors.
- Internal R&D and Service Support: NVIDIA can lease CoreWeave's servers for internal R&D, while CoreWeave's servers also support NVIDIA DGX Cloud computing services.
2.2 OpenAI's Compute Diversification and the "Arms Race"
As a leader in the AI field, OpenAI's demand for compute power is growing exponentially. Sam Altman once stated that OpenAI would be "the most capital-intensive startup in human history." To realize its ambitions for AGI (Artificial General Intelligence), OpenAI has actively sought diversified compute sources:
- Deep Collaboration with Microsoft: Microsoft has invested over $13 billion in OpenAI, gaining approximately 20% revenue share and IP rights (until AGI is achieved). OpenAI also pays billions of dollars annually to Microsoft for cloud services. However, due to Microsoft's slow compute supply, OpenAI began seeking other partners.
- Rumored Cooperation with Google TPU: OpenAI was rumored to have started leasing Google's TPU chips to support products like ChatGPT, aiming to reduce costs and dependence on NVIDIA and Microsoft. Although OpenAI later clarified that "there are no concrete plans to use TPUs at present," this move reflected its willingness to seek alternatives.
- Stargate Project with Oracle: OpenAI, in collaboration with Oracle, SoftBank, and MGX, launched the Stargate project, planning to invest $500 billion over four years to build new AI infrastructure, with the first $100 billion earmarked for the expansion of the Oracle/Crusoe data center in Texas Abilene. Oracle, with its unique "hybrid" data center strategy and cost advantages, has achieved success in the AI computing market and established a long-term partnership with OpenAI.
- Self-Developed ASIC Chips: OpenAI also plans to collaborate with Broadcom and TSMC to develop chips for running AI models, expected to debut as early as 2026, to reduce reliance on NVIDIA.
OpenAI and NVIDIA Executives Group Photo
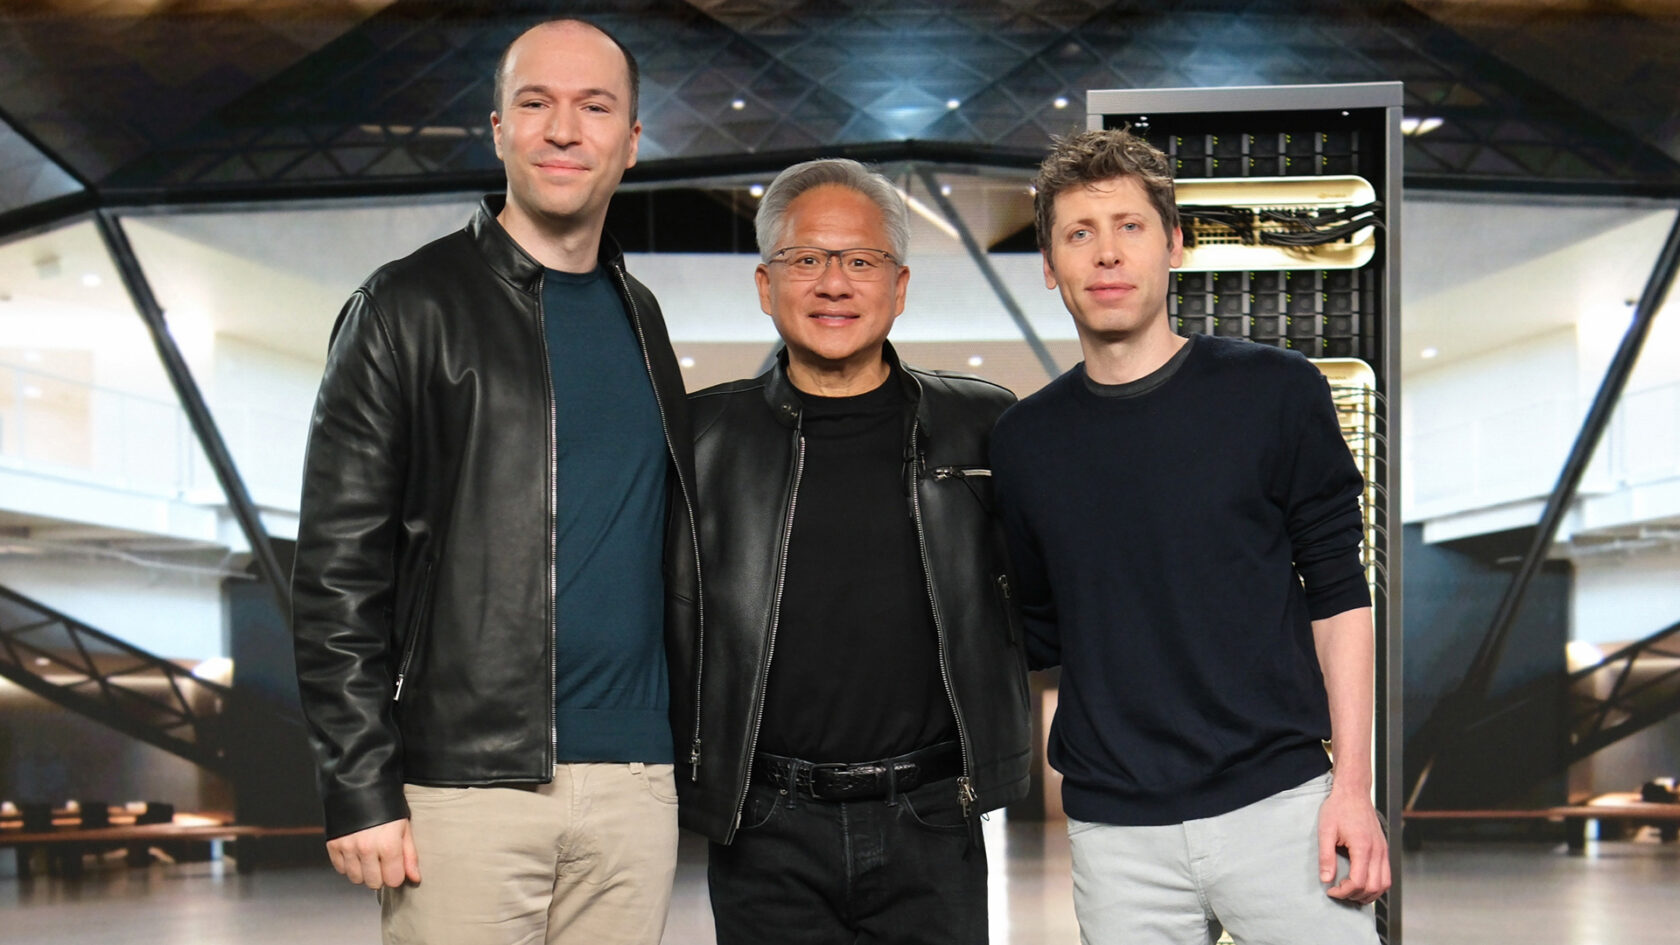
Source: Nvidia
These initiatives by OpenAI indicate that in the AGI "arms race," securing sufficient, efficient, and cost-effective compute power is its core strategy.
3. Market Competition and Future Landscape: The Co-opetition Between GPUs and ASICs
NVIDIA dominates the AI compute market, with its GPUs becoming the industry standard due to their powerful performance and comprehensive CUDA ecosystem. However, many believe that this 90% market share cannot be sustained in the long run, and the future will see fragmentation by ASICs and self-developed projects.
- ASIC Challenges and Opportunities: Theoretically, self-developed ASICs can reduce costs, but in practice, competing with NVIDIA is difficult. Tesla's cancellation of the Dojo project confirms the difficulty of self-developed chips. However, as the focus of AI applications shifts from training to inference, the demand for high-performance, large-memory GPU clusters becomes a new competitive focal point, opening opportunities for alternative silicon solutions such as Google's TPUs, AWS Trainium, Azure Maia 100, and products from Groq and Cerebras.
- NVIDIA's Continuous Innovation: NVIDIA continuously enhances the performance and Total Cost of Ownership (TCO) advantages of its chips by consistently introducing new generations of GPUs (e.g., Blackwell architecture's GB200) and rack-scale integrated systems (e.g., GB200 NVL72 platform). The GB200 system has demonstrated 2 to 3 times the performance improvement over its predecessor, the H100 chip, in MLPerf benchmarks, even helping Cohere achieve up to 3 times performance improvement in specific model training.
- Competitors' Efforts:
- Google's TPU has evolved to v7, featuring efficient networking and a fully integrated stack, resulting in the lowest cost per token. Google also began selling TPUs externally through Google Cloud Platform, with Anthropic as one of its customers.
- AMD's MI300 series is excellent in design, but its software ecosystem (ROCm)'s ease of use is a weakness. Nevertheless, AMD has established partnerships with cloud companies like Oracle, Amazon, and Crusoe through a "sale-leaseback strategy," attempting to gain market share.
- Meta's MTIA chip focuses on recommendation systems, accounting for over 50% of Meta's internal capital expenditure.
4. Risks and Uncertainties: Prudent Considerations for Large-Scale Investments
Despite the promising outlook for the NVIDIA-OpenAI partnership, it is accompanied by potential risks and uncertainties:
- Accounting Treatment and Market Perception: BofA notes that such a large-scale investment in a customer might raise market questions regarding its "perception" until NVIDIA clarifies appropriate accounting methods. While NVIDIA might treat it as an equity investment or a regular commercial customer, the transparency of this model still warrants attention.
- Transaction Certainty: Morgan Stanley views this transaction as depicting a long-term "bull case scenario" vision rather than a "certain event," primarily due to "the enormous figures involved" and OpenAI's recent other large-scale transactions with companies like Oracle (over $300 billion+ deal). This suggests that despite the LOI being signed, actual execution and ultimate revenue contribution may still be subject to change.
- Power and Infrastructure Limitations: The construction of AI data centers faces significant power availability challenges. Goldman Sachs estimates that by 2030, the U.S. will require approximately 47GW of new power generation capacity to support the increasing data center power demand. OpenAI's Stargate project, whose final phase may require as much as 5GW of power, poses severe challenges for power supply.
- Intensified Competition and Technological Iteration: The preferential partnership between NVIDIA and OpenAI might increase competitive risks for other suppliers like AVGO and AMD. Simultaneously, the rapid iteration of AI technology means that today's leading edge could quickly be disrupted.
5. Conclusion and Outlook: Long-Term Trends in AI Infrastructure Investment
NVIDIA's investment in OpenAI marks another milestone in the AI era's compute "arms race." It not only highlights NVIDIA's unshakeable leadership position in AI infrastructure but also reveals the diversified, even aggressive, strategies adopted by AI giants like OpenAI to secure core compute power.
This "customer financing" model, through equity investment and deep collaboration, enables NVIDIA to more closely tie in key customers, accelerate market penetration of its GPUs and platform technologies, and effectively utilize its massive FCF. Concurrently, it prompts customers like OpenAI to drive innovation and development across the entire AI infrastructure ecosystem in their pursuit of compute diversification.
Despite facing challenges such as accounting treatment, transaction certainty, and power limitations, the long-term trend in AI infrastructure investment is clear. As AI moves from laboratories to the world, the demand for high-performance computing will continue to grow. Enterprises capable of providing full-stack solutions and flexibly adjusting their business models, like NVIDIA, are poised to maintain leadership in this industrial revolution. The future AI compute market will be a complex landscape of GPU and ASIC co-opetition, with hyperscale vendors and "neo cloud" companies coexisting.


